
Philippines staffing research
Billing Close Control-Total Research: Can the Package Be Rebuilt From Frozen Sources?
A reproducibility study of frozen extracts, population totals, adjustments, exceptions, approvals, reruns, and the final month-end billing package.
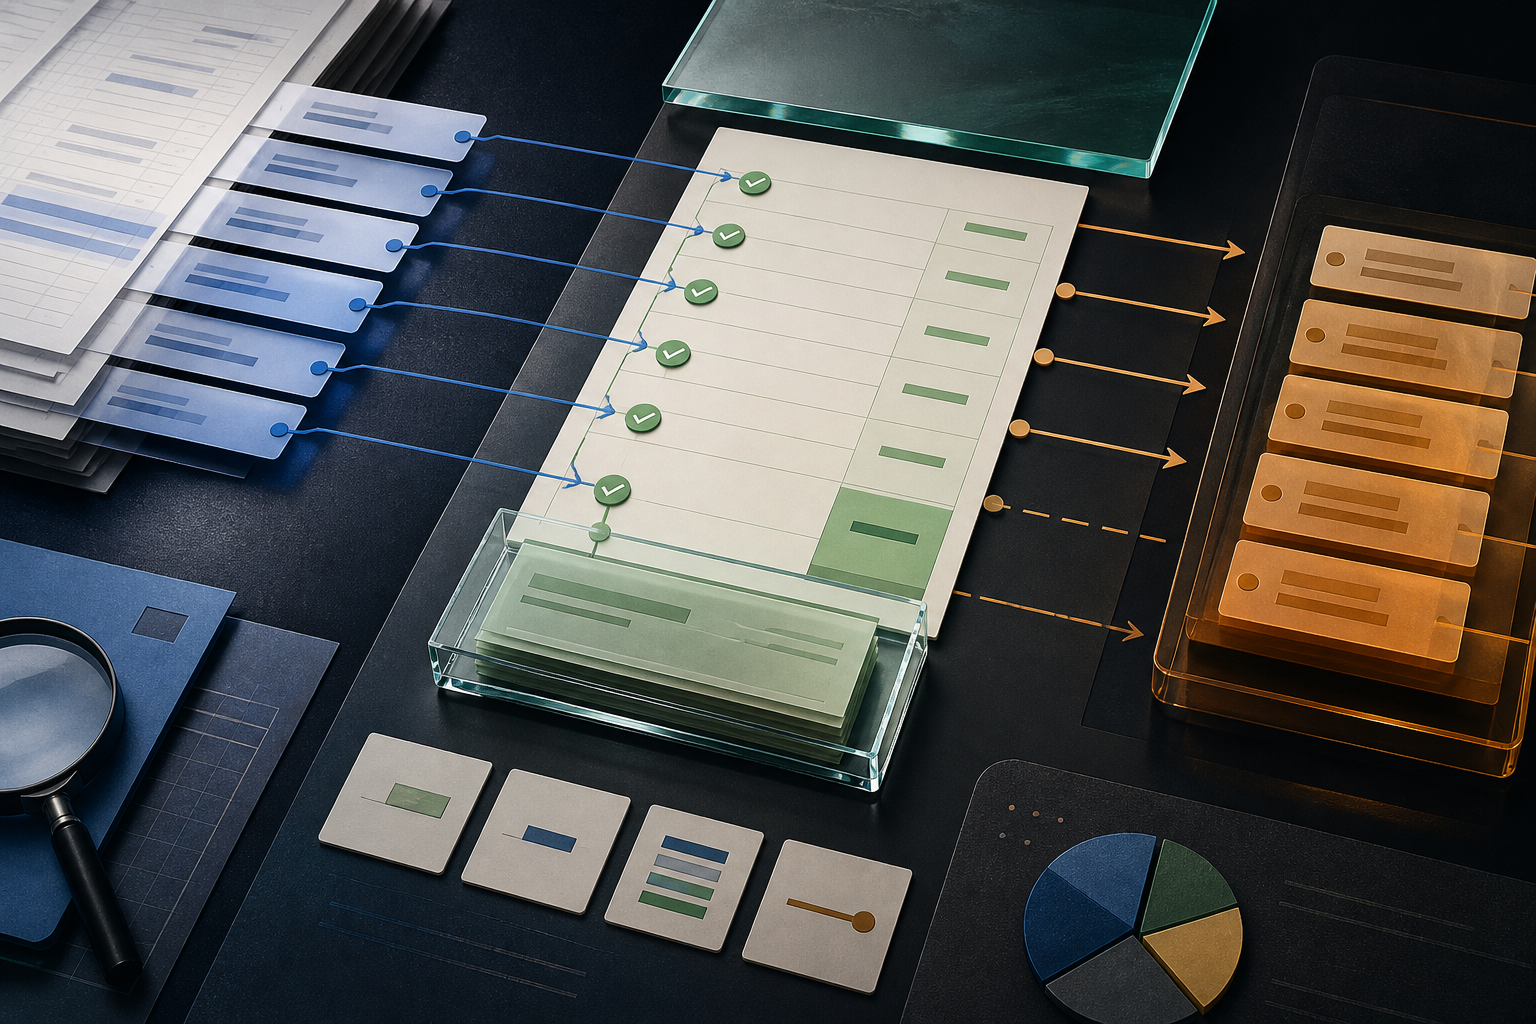
A month-end billing package can balance internally and still be impossible to reproduce. A pasted total may omit a source population, two reports may use different cutoffs, or a late rerun may replace the preliminary evidence. Control-total research therefore begins with the claim each number makes: which records, measure, currency, cutoff, source version, and transformation produced it?
The study asks whether a second reviewer can rebuild every declared billing close total from frozen named inputs and explain movement between preliminary and final versions. It informs whether source preparation and reconciliation can be delegated. It does not set materiality, approve a close, post an entry, make an estimate, interpret accounting policy, or offer an audit opinion.
Use one declared control total as the unit. A row count, invoice value, credit value, unapplied-cash amount, unbilled count, exception count, and held population are separate units even when they appear in one workbook. Each needs a source, grain, sign convention, currency, cutoff, and calculation.
Inventory every claim in the package before testing calculations. Record its purpose, displayed label, source system, report or query, parameters, extraction timestamp and timezone, row count, amount, currency, protected input locator, transformation steps, exclusions, preparer, reviewer, and downstream recipient. A screenshot shows what someone viewed but cannot replace the retained input required for reproduction.
Freeze inputs before review. Mutable reports should be exported under controlled parameters, with extraction time and version evidence. If retention policy prevents copying detailed data, use an approved protected locator and preserve enough control information to retrieve the same version. An unavailable source stays in the denominator as not reproducible.
Build a dependency map from sources through intermediate schedules to presented totals. This reveals when several totals depend on one transformed file or manual workbook. Test the earliest reusable transformation as well as each final output; otherwise the same defect can appear to be several independent differences.
Compare row counts before money. A total amount can agree while one positive and one negative record are missing. Reconcile distinct record keys, duplicate handling, signs, document types, currencies, and zero-value records. Never combine currencies into a nominal grand total unless an approved conversion is separately evidenced.
Recalculate formulas from retained inputs. Inspect filters, joins, lookups, date boundaries, status selections, hard-coded values, and formula-to-value replacements. Preserve both the written method and executable artifact where possible. Agreement with a pasted number is not reproduction when the underlying calculation cannot be observed.
Version movement is a separate research object. Suppose a preliminary invoice register contains 5,100 records. Late approvals add 60, cancellations remove 12, a corrected import replaces 20 records, and an owner approves one manual adjustment. The final count cannot be explained by saving over the preliminary file. A movement schedule shows the exact additions, removals, replacements, and judgment separately.
For that example, preserve preliminary total, each late-record key, cancellation evidence, old and new import versions, approved adjustment, rerun parameters, and final total. Reproduce the bridge at record and value level. The study does not decide whether the late records belong in the accounting period; it shows the operational effects available to the owner.
Late arrivals must not be inserted silently into the frozen opening population. Record observation time, asserted effective time, source, affected control, amount and currency, duplicate check, and owner disposition. Classify as approved current-version movement, carry-forward, unresolved, or another client-defined state. Keep the original package intact.
Adjustments need explicit lineage. Separate source-data corrections, operational classifications, and owner judgments. Store the proposed value, rationale, source, affected total, approving role, time, and implementation reference. A workbook note saying adjustment is insufficient when another reviewer cannot locate the authority or reproduce its effect.
Reruns require idempotency and recipient control. Record why the rerun occurred, which jobs were disabled, input versions, new output identifiers, difference from the prior run, and destinations receiving the superseding package. Search for duplicate invoice candidates or exports created by repeated execution.
Classify each total as reproducible, source unavailable, parameter mismatch, row-count mismatch, amount mismatch, currency mixed, exclusion unsupported, late movement disclosed, adjustment approved, rerun linked, pasted or opaque calculation, owner review pending, superseded, signed off, or unresolved. A package-level pass should not erase failed totals.
A second reviewer rebuilds totals from the frozen locators and written parameters without using the preparer’s presented result as an input. Record their calculated value, difference, evidence consulted, and any rule ambiguity. When a rule changes after results appear, rerun it consistently and preserve both versions.
Spreadsheet review should look beyond visible formulas. Inspect hidden rows or sheets, named ranges, external links, stale cached values, manual sorting, copied formulas, and cells containing constants where formulas are expected. The aim is not to certify the software; it is to identify whether the claimed transformation can be followed.
Downstream equality matters. Compare the approved close output with files or schedules delivered to finance, operations, and reporting owners. Use hashes or record-level totals where appropriate. A reproducible internal package can still fail at export or version selection.
Exception closure should identify the exact total and assertion repaired. After a query, formula, exclusion, or source is corrected, rerun the affected dependency path from frozen inputs and compare the new output with the authorized movement. Confirm that unrelated totals remain stable. A general note that the workbook was updated cannot demonstrate which evidence changed or whether the original difference persists.
Negative and zero populations deserve explicit tests. Credit values, reversals, cancellations, and zero-dollar documents can be dropped by filters intended for ordinary invoices. Recalculate signed totals and absolute activity separately where useful, then inspect zero-value records that still affect counts or workflow. Do not remove them merely because they have no net monetary effect.
Report reproducibility by declared total, not merely workbook. Disclose inaccessible sources, parameters that could not be recreated, unsupported exclusions, late movements, opaque calculations, and unresolved differences. Include numerator and denominator with any rate. A high percentage is misleading if omitted high-value totals disappear from scope.
Elapsed-time measures should distinguish source availability, preparation, reviewer reproduction, owner decision, correction, and downstream acknowledgment. Define each endpoint and report missing timestamps. A delayed sign-off may reflect an unresolved owner judgment rather than slow calculation work.
Access should be limited to the systems, extracts, and schedules needed for preparation. Approval, journal posting, permission administration, and final sign-off remain separated according to the buyer’s control design. Protect customer and financial information under approved retention and transfer practices.
The buyer receives a dependency map, frozen source inventory, movement bridge, and total-level exception register. Those artifacts reveal whether the package can be rebuilt and where evidence becomes unavailable or judgment begins. They can support better extraction, review, handoff, and version control without claiming that reproducibility establishes accounting correctness.
Standards for Internal Control in the Federal Government: 2025 Revision. U.S. Government Accountability Office. https://www.gao.gov/greenbook. Checked October 5, 2026. Used for quality information, control documentation, reconciliation, and monitoring.
Security and Privacy Controls for Information Systems and Organizations, SP 800-53 Revision 5. National Institute of Standards and Technology. https://csrc.nist.gov/pubs/sp/800/53/r5/upd1/final. Checked October 5, 2026. Used for audit records, information integrity, access, and configuration control.
Revenue Recognition: ASU 2014-09, Revenue from Contracts with Customers (Topic 606). Financial Accounting Standards Board. https://fasb.org/projects/recently-completed-projects/revenue-recognition-summary. Checked October 5, 2026. Used only to identify accounting matters reserved to qualified owners.